Understanding borrowing costs
0% APR and deferred interest: one difference that can cost you
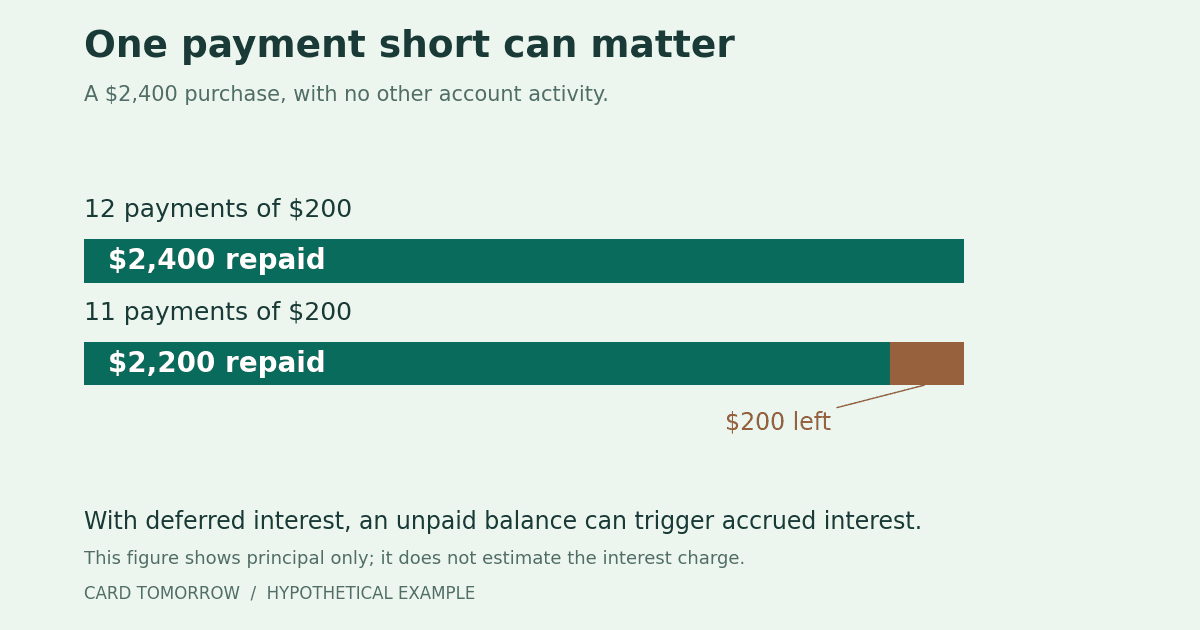
Learn what happens to an unpaid balance when a 0% APR promotion ends, how deferred interest differs, and how to set a payoff deadline with room to spare.
A headline rate does not tell you what borrowing will cost. Work through the promotion, fees and payment dates before choosing a repayment plan.
8 guides · Page 1 of 2
Learn what happens to an unpaid balance when a 0% APR promotion ends, how deferred interest differs, and how to set a payoff deadline with room to spare.
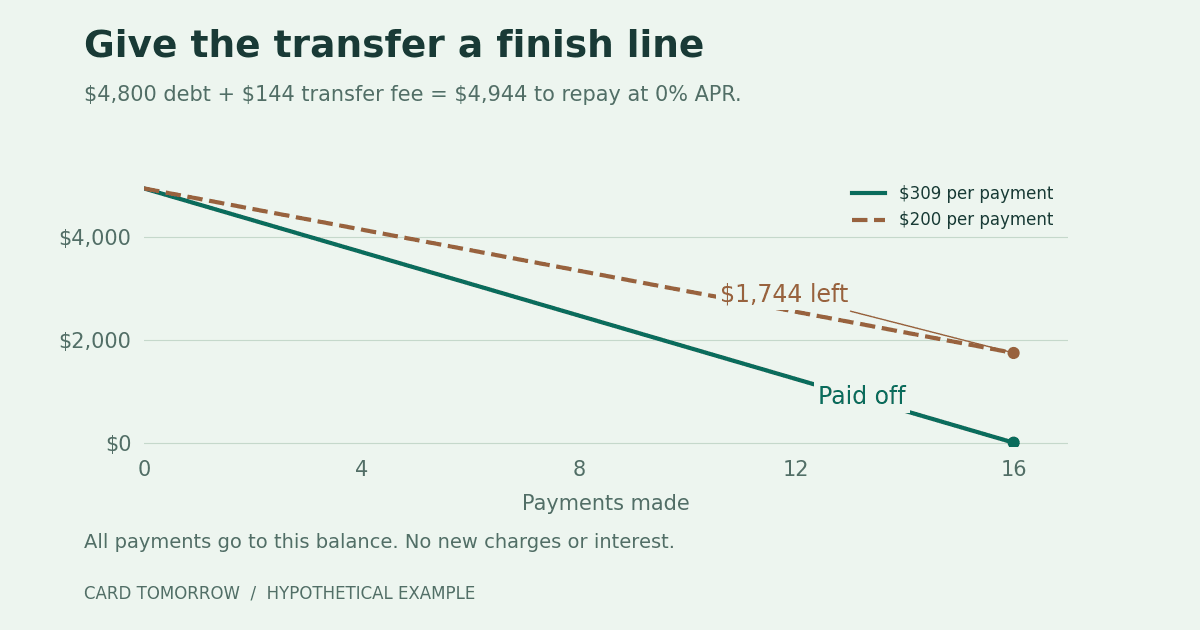
Turn a balance-transfer fee and an end date into a realistic payoff plan. See how a $4,800 transfer becomes a $309 payment over 16 payment dates.
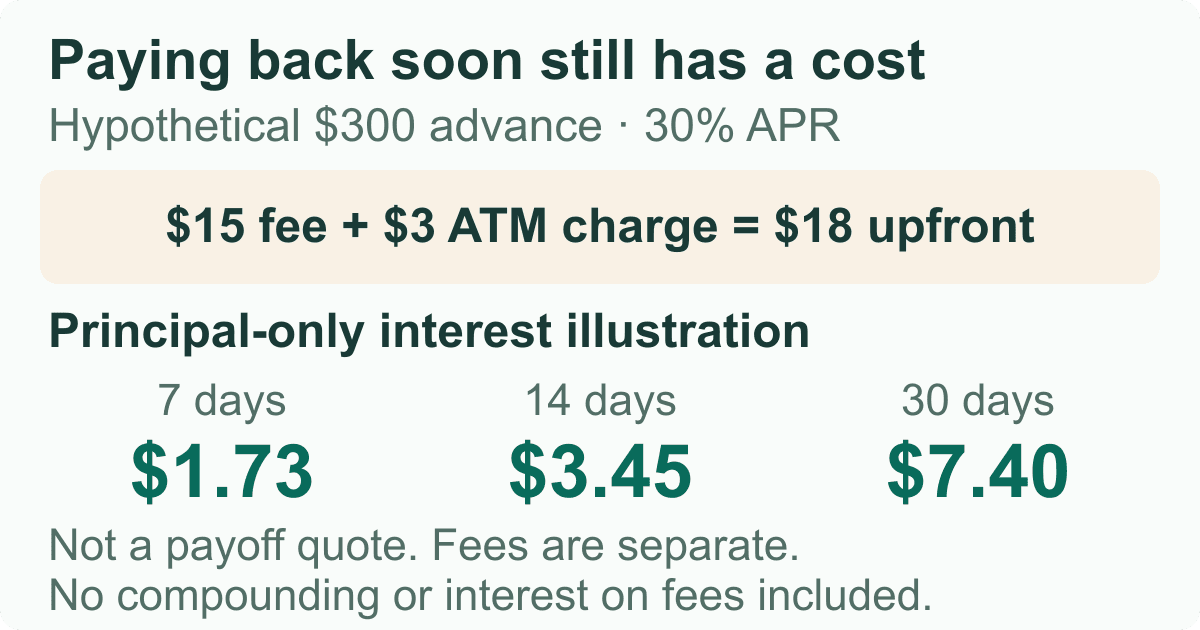
See why a short borrowing period does not remove cash-advance fees, with a clearly qualified example separating upfront charges from daily interest.
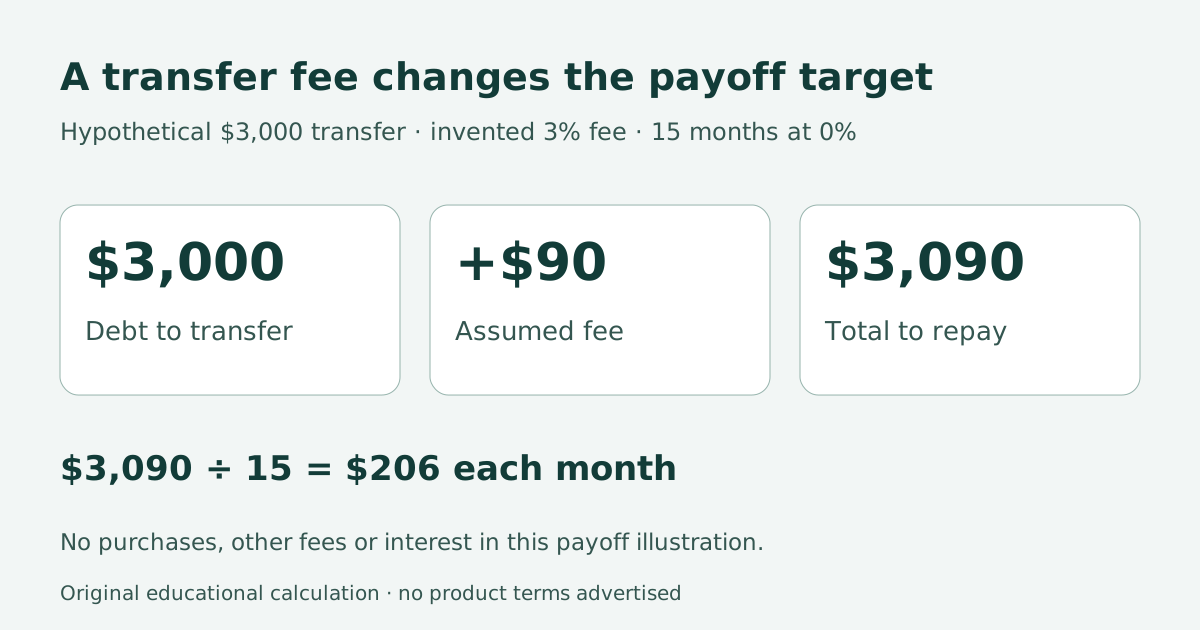
Compare a transfer fee with a declining-balance interest estimate, then check whether your budget can clear the transferred debt before the introductory period ends.
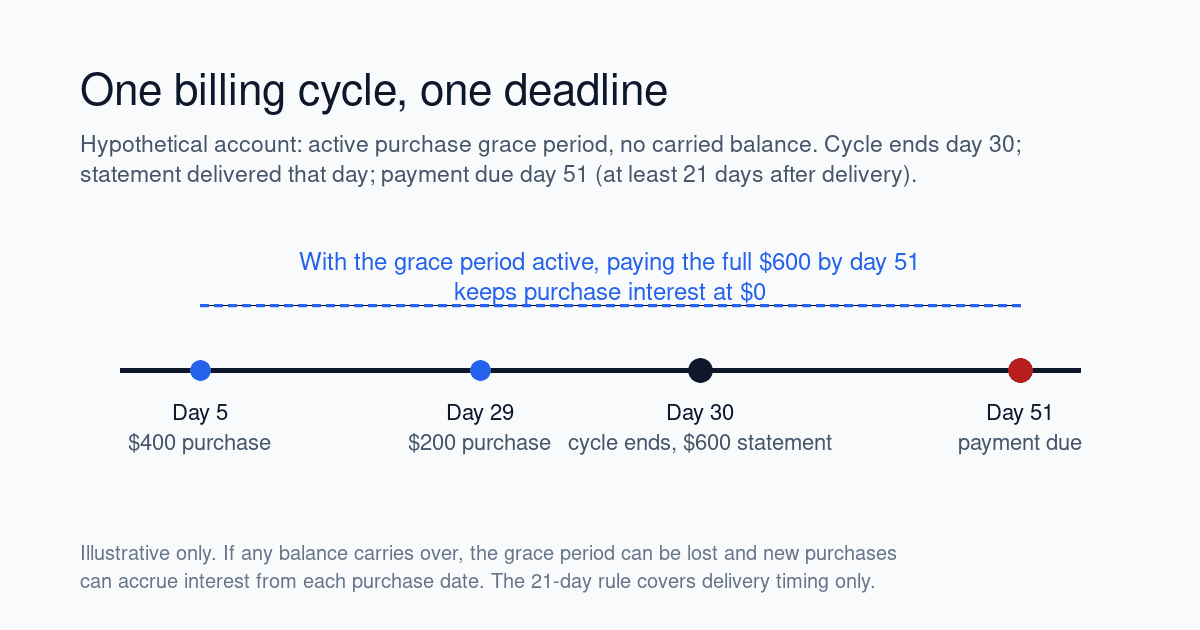
A dated explainer on when purchases avoid interest, how the grace period is lost, and why other balances behave differently.
A statement closes on one date and a payment arrives on another. That gap can explain a remaining interest charge on a carried balance.
Educational articles, with original examples. Check an offer’s current terms with its provider before applying.
Our editorial standards →Subscribe by RSS →