An upgrade possibility is not a refund date
A secured-card deposit can be refundable without having a known return date. If you are considering an upgrade or another account change, find out what triggers the return and how the money reaches you. Until those terms are established and the refund arrives, keep that money out of the cash you plan to spend.
Two official product pages checked on October 29 describe refundable deposits and a path to an unsecured account. One says you could earn back the deposit and upgrade. Another connects earning the deposit back and upgrading with establishing a positive track record. Neither supplied excerpt gives a review schedule, a firm decision date or a refund delivery timetable. Those missing details matter when the deposit is part of a tight budget.
Separate the deposit from the credit line
The deposit and the credit line are different figures to check. One cited page lists minimum refundable deposits of $49, $99 or $200. Another describes a refundable deposit as low as $49 and credit lines starting at $200. Those descriptions do not establish which deposit or credit line a particular applicant will receive.
Write down the required deposit, the resulting credit line and any conditions for receiving those terms. Do not assume that “as low as” applies to you, or that the deposit will always equal the line. If the required deposit is larger than you expected, reconsider using money needed for immediate expenses. A refundable amount can still be unavailable when your household needs it.
Keep a cash plan while the deposit is held
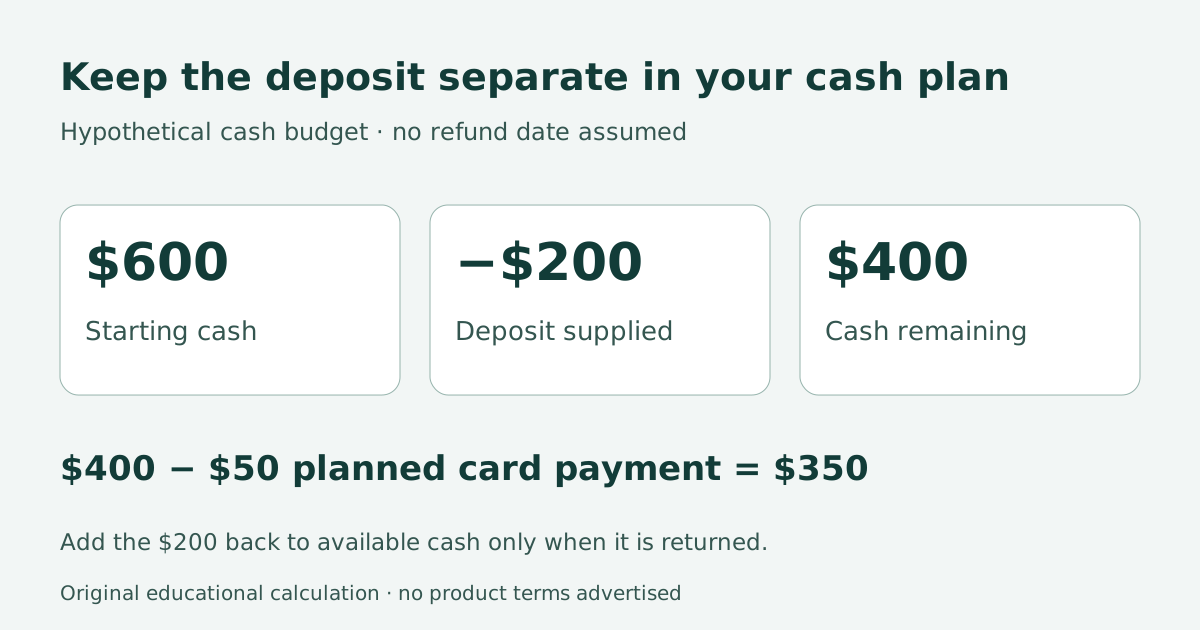
Consider a hypothetical person with $600 of available cash who supplies a $200 deposit. Their remaining cash is $400. If they also plan a $50 card payment from that cash, the amount left for other expenses becomes $350. This illustration treats the payment as a separate outflow and assumes the deposit has not been returned or applied to anything.
If the $200 later comes back, available cash increases by $200 at that point. Counting it earlier would overstate the money available for groceries, rent or another bill. A potential upgrade does not change this arithmetic. Keep the deposit in a separate line of your budget, labeled unavailable until returned, rather than quietly including it in your bank balance forecast.
Ask what actually changes at an upgrade
The checked pages support a possible transition to an unsecured account, but they do not supply the full mechanics. Before relying on an upgrade, ask what criteria apply, whether a review is automatic, whether you must request it and how you will learn the outcome. A reference to a positive track record is not a complete checklist or a guaranteed timetable.
Also ask what happens to the account itself. Will the account identifier, credit line, rate, fees or other terms change? Will the deposit be returned in full, and through which method? These are questions for the provider, not outcomes established here. Save the written response and any new agreement. If a detail is important to your decision, resolve it before treating the change as finished.
Get separate answers before closing
An upgrade and a closure are different requests. The excerpts describe refundable deposits and upgrade possibilities; they do not describe what happens to a deposit when an account closes. They establish no right to an immediate cash refund, no order for applying funds and no universal number of days to wait.
Before closing, ask how any remaining balance affects the deposit, whether pending transactions change the amount returned and how the final calculation will be communicated. Confirm the address or account used for any return and the expected timing. Do not schedule an essential expense around a guessed refund date. If you need the deposit for that expense, ask for the applicable procedure while you still have time to plan around uncertainty.
Compare ongoing cost as well as tied-up cash
Both cited product pages describe no annual fee. That is a useful comparison point, but it is a single fee term. Keep each product’s deposit requirements attached to its own terms. There is no basis for filling a gap in one account’s terms with another account’s deposit figure, review policy or refund procedure.
For your own comparison, keep separate columns for annual fee, deposit required, credit line offered and the terms governing deposit return. Request any other costs that matter to your planned use. Do not turn a no-annual-fee statement into an assumption that every transaction or borrowing choice has no cost. A deposit you expect to recover also has a different budgeting effect from a fee you pay for the account.
Track the return until it is complete
When a provider confirms a change, retain the notice and record the promised return method, amount and timing. Check the actual result against that record. If the money has not arrived when the provider said it should, ask for the status using the account’s official support channel. Keep the explanation with your account records so the next conversation starts with concrete facts.
Choose an account using the deposit you can afford now and the written terms you can verify, rather than an assumed upgrade date. For an existing account, identify the exact change you want, get its deposit-return procedure and keep your cash plan conservative until the return is complete. That approach lets an eventual refund improve your budget without making today’s essential payments depend on an unconfirmed outcome.
Keep the original deposit confirmation too. It gives you a starting figure for checking the provider’s explanation of the eventual return. If an amount differs, request an itemized explanation rather than assuming the entire deposit is either lost or immediately payable. The answer needs to come from the account’s applicable terms and actual history.
Sources and further reading
Sources checked October 29, 2026.
- Official provider product page: refundable deposits and possible unsecured upgradeOperator source pack: fetched October 29, 2026, 8:38–8:40 p.m. EDT; publication/effective date not supplied.
- Official provider product page: refundable deposit, starting credit line and upgrade descriptionOperator source pack: fetched October 29, 2026, 8:38–8:40 p.m. EDT; publication/effective date not supplied.